If you’ve been wondering what your budget can actually get you in today’s market, you’re not alone. One of the first questions I get from buyers is:“What does my price point

Dated: September 15 2026
Views: 1
Finding your dream home and getting an accepted offer is exciting. However, there is still one important step before closing: the appraisal.
Many buyers and sellers are surprised to learn that a home's appraised value can impact the entire transaction. So what happens if a home appraises for less than the agreed-upon purchase price?
Let's break it down.
A home appraisal is an independent opinion of a property's market value conducted by a licensed appraiser. The lender orders the appraisal to ensure the home is worth the amount being financed.
The appraiser evaluates the property's condition, size, features, upgrades, location, and recent comparable sales in the area.
Lenders base their loan amount on the lower of the purchase price or the appraised value.
For example:
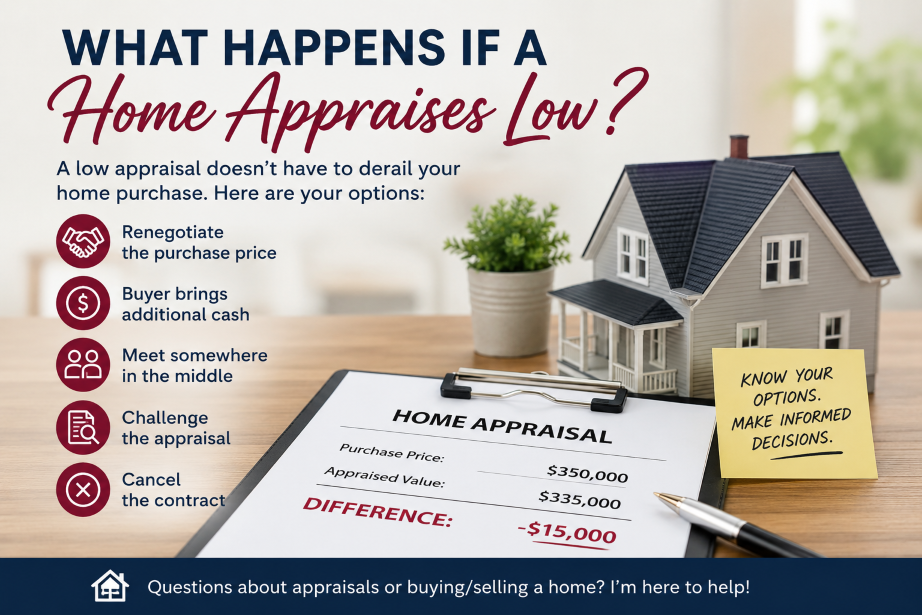
Purchase Price: $350,000
Appraised Value: $335,000
The lender will use the $335,000 value when calculating the loan amount.
This creates a $15,000 gap that must be addressed before the transaction can move forward.
One of the most common solutions is for the seller to reduce the purchase price to match the appraised value.
Using the example above, the seller may agree to lower the price from $350,000 to $335,000.
This allows the buyer to move forward without bringing additional funds to closing.
If the buyer still wants the home and the seller is unwilling to reduce the price, the buyer can choose to bring additional cash to cover the difference.
For example, if the appraisal comes in $15,000 low, the buyer could pay that amount out of pocket in addition to their down payment and closing costs.
Not all buyers have the ability or desire to do this, but it can be a solution in competitive markets.
Sometimes buyers and sellers negotiate a compromise.
Using the same example, the seller might reduce the price by $7,500 and the buyer might bring an additional $7,500 to closing.
This allows both parties to share the burden of the appraisal gap.
If there are concerns that the appraiser missed important comparable sales or overlooked significant improvements, the lender may allow a reconsideration of value request.
While appraisals are not often changed significantly, providing additional market data can sometimes result in adjustments.
Many purchase agreements contain an appraisal contingency that protects the buyer if the property does not appraise.
If an agreement cannot be reached between the buyer and seller, the buyer may have the option to cancel the contract and receive their earnest money back, depending on the terms of the purchase agreement.
While sellers cannot control the appraisal, they can help support value by:
• Providing a list of recent improvements and upgrades
• Keeping the home clean and well-maintained
• Sharing information about multiple offers when appropriate
• Ensuring the appraiser has access to all areas of the property
A low appraisal does not necessarily mean you are paying too much for a home.
Appraisals are based on historical sales data, while market conditions can change quickly. In a rising market, it is not uncommon for appraisals to come in below contract price.
The key is working with an experienced real estate professional who can help navigate the options and negotiate a solution that works for everyone involved.
A low appraisal can feel stressful, but it doesn't have to derail your home purchase.
Whether it's renegotiating the price, challenging the appraisal, or finding another solution, there are often several paths forward.
If you're buying or selling a home and have questions about appraisals, I'd be happy to help you understand your options and guide you through the process.
Connie Stegora Homes
MBA, GRI, MRP, AHWD
Keller Williams Classic Realty NW
612-812-2870
Hi, I'm your local Minnesota Realtor®, proudly serving Monticello, Big Lake, Sherburne County, Wright County, and surrounding areas. Whether you're buying your first home, upgrading, downsizing, o....
If you’ve been wondering what your budget can actually get you in today’s market, you’re not alone. One of the first questions I get from buyers is:“What does my price point
Finding your dream home and getting an accepted offer is exciting. However, there is still one important step before closing: the appraisal.Many buyers and sellers are surprised to learn that a home
Owning a waterfront property is a dream for many people.Owning a waterfront property is a dream for many people. Whether you’re looking for a year-round home, a weekend cabin, or an investment
 The data relating to real estate for sale on this web site comes in part from the Broker Reciprocity Program of the Regional Multiple Listing Service of Minnesota, Inc. Real estate listings held by brokerage firms other than Keller Williams Classic Realty NW - Connie Stegora are marked with the Broker Reciprocity logo or the Broker Reciprocity thumbnail logo (little black
house) and detailed information about them includes the name of the listing brokers.
The broker providing these data believes them to be correct, but advises interested parties to confirm them before relying on them in a purchase decision.
© 2026 Regional Multiple Listing Service of Minnesota, Inc. All rights
reserved
By searching, you agree to the End User License Agreement.
Digital Millennium Copyright Act (DMCA) Notice
The Digital Millennium Copyright Act of 1998, 17 U.S.C. 512 (the "DMCA"), provides recourse for copyright owners who believe that material appearing on the Internet infringes their rights under U.S. copyright law. If you believe in good faith that any content or material made available in connection with our website or services infringes your copyright, you (or your agent) may send us a notice requesting that the content or material be removed, or access to it blocked. Notices and counter-notices should be sent in writing by mail to Michael Bisping, Director, Customer Relations, Regional Multiple Listing Service of Minnesota, Inc, 2550 University Avenue West, Suite 259S
Saint Paul, MN 55114 or by email to mbisping@northstarmls.com. Questions can be directed by phone to 651-251-3200.
